
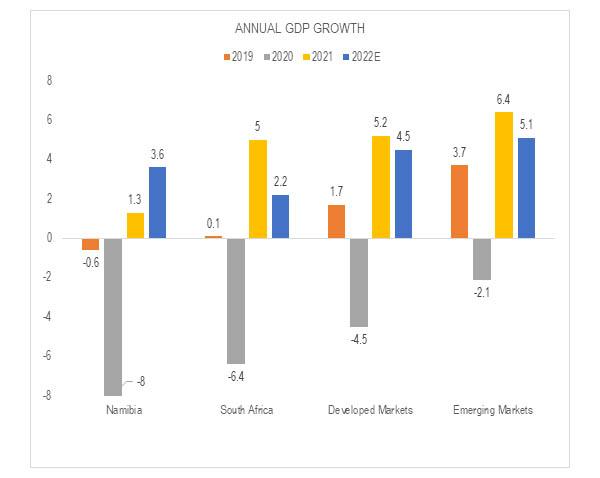
The IMF revised their GDP growth last quarter with the only upward revision being developed markets. In the previous revision they indicated that the economic recovery has lost some momentum amidst the concern around the delta variant, strained supply chains, accelerating inflation and the rising costs for food and fuel. The expectation for world GDP is 4.9% for 2022. The expected growth for GDP in Namibia, South Africa, Developed Markets and Emerging Markets is illustrated in figure 1 below.
The MSCI World Index is measured in USD terms and the USD/ZAR for the fourth quarter averaged at R15.41, the lowest USD/ZAR for the quarter was on 15 October 2021 at R14.60 and the highest USD/ZAR was on 3 December 2021 R16.08. At the time of writing the USD/ZAR is trading at R15.46, indicating a weaker rand going forward.
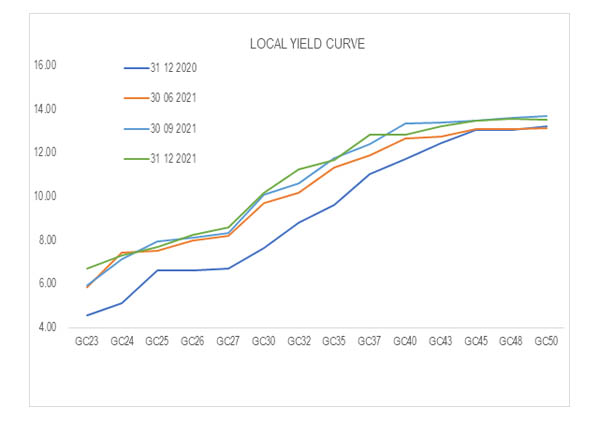
The yield curve is still sloping upward and steep, although slightly less steep than the previous quarter. In 2022 we expect the curve to steepen as inflation pressure realises.
In 2022 all equity markets had positive returns with the exception of the Hang Seng, see below. The same can be said for the fourth quarter returns. The JSE All Share Index “JALSH” returned 16.3% for the quarter (2020 +9.4%) and the MSCI World Index returning 7.3% for the quarter (2020 +13.4%).
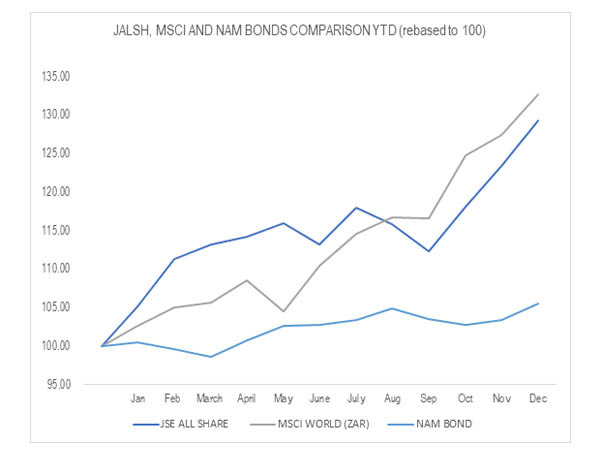
At the start of the quarter, the JSE All Share Index went on a rally reaching a high of 73 709 index points. At the time of writing this article it is trading at 76 788 index points. The MSCI World Index ended the year at an all-time high on the 31st of December 2021 trading at 3 231 points and has since dipped slightly to 3 054 points at the time of writing this article.
The best performing sectors on the JSE All Share Index for the year was Energy (+111.4%), Communication Services (+98.4%) and Consumer Discretionary (+77.3%). The worst performer was Information Technology which lost 17.9% for the year. The cheapest sector continues to be Energy with the lowest PE at 3.1x and highest dividend yield at 20.8% and the most expensive sector continues to be Information Technology with a PE of 17.8x and a dividend yield of 1.9%. See table 1 below:

The MSCI World best sector performance for the year was Energy (+41.8%), Information Technology (+30.1%) and Real Estate (+29.5%). The worst performing sector was Consumer Staples (+13.7%). The cheapest sectors for the year were Materials with an average PE of 9.0x and a dividend yield of 3.5% and the most expensive being Information Technology with a PE of 27.9x and dividend yield of 0.9%. See table 2 below.

